Semiconductor IP Market Growth: Increasing Chip Complexity Fuels Demand for Reusable IP
The global Semiconductor IP Market is expanding as chip designers and foundries increasingly invest in processor cores, interface IP, AI accelerators, security blocks, and custom silicon solutions for advanced SoCs.
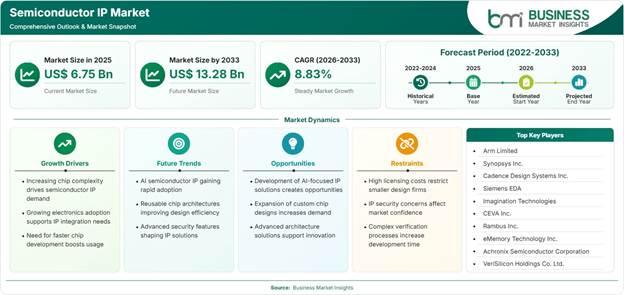
According to Business Market Insights, the Semiconductor IP Market size was valued at US$ 6.75 billion in 2025 and is projected to reach US$ 13.28 billion by 2033, growing at a CAGR of 8.83% during 2026–2033.
Download Sample Report: https://www.businessmarketinsights.com/sample/BMIPUB00038096
Semiconductor IP Market Drivers
Increasing Chip Complexity
Increasing semiconductor complexity is one of the primary drivers of semiconductor IP adoption. Modern SoCs can integrate processor clusters, memory controllers, high-speed interfaces, accelerators, security modules, connectivity technologies, and specialized processing functions within a single architecture.
Developing every functional block internally can significantly increase engineering requirements, verification workloads, development time, and cost. Reusable IP provides semiconductor designers with access to validated building blocks, allowing them to focus internal resources on differentiated components and application-specific functionality.
Growing Electronics Adoption
The expansion of consumer electronics, telecommunications equipment, automotive electronics, industrial systems, smart devices, and edge computing is increasing semiconductor content across multiple applications. Each generation of electronic products is incorporating more processing, sensing, memory, connectivity, and security functions.
This trend is creating recurring demand for reusable semiconductor IP. IP vendors can help design teams integrate mature technologies into new chip architectures without recreating established functionality, supporting faster product development and greater architectural flexibility.
Shorter Chip Development Cycles
Semiconductor companies increasingly face pressure to commercialize new products quickly as technology cycles shorten and application requirements evolve rapidly. Developing complex IP internally can extend design timelines and increase verification requirements.
Reusable third-party IP allows semiconductor companies to accelerate architecture development by integrating pre-developed and validated building blocks. This is particularly important for AI accelerators, networking chips, automotive processors, custom silicon, and application-specific SoCs.
Expansion of Custom Silicon
Technology companies and system manufacturers are increasingly pursuing custom silicon to optimize performance, power efficiency, workloads, and software integration. Custom chip programs do not necessarily require every architectural component to be developed internally.
External processor, interface, memory, security, and connectivity IP can therefore support custom silicon programs while allowing companies to concentrate their engineering resources on proprietary accelerators and differentiated architectures.
Semiconductor IP Market Opportunities
AI-Focused Semiconductor IP
The rapid expansion of AI workloads is creating opportunities for specialized processor, neural acceleration, memory, and interconnect IP. AI computing requires efficient data movement, parallel processing, specialized acceleration, and optimized memory architectures.
IP vendors can capture opportunities by developing configurable neural engines, domain-specific processors, efficient memory systems, and high-bandwidth interfaces that can be integrated into customer-specific AI SoCs.
Chiplet and Heterogeneous Architectures
Chiplet architectures are creating a new opportunity for semiconductor IP providers because multiple dies and specialized processing elements must communicate efficiently within advanced systems. High-speed interconnect and interface IP are becoming increasingly important as chip designers move beyond conventional monolithic SoC architectures.
Vendors that provide protocol-compatible, secure, scalable, power-efficient, and validated interface technologies can benefit from increasing adoption of heterogeneous integration and advanced packaging.
Automotive Computing Platforms
The automotive industry is becoming a significant opportunity for semiconductor IP providers as vehicles incorporate increasingly sophisticated electronic architectures. Advanced driver assistance systems, software-defined vehicles, connected systems, autonomous technologies, and centralized computing platforms require powerful processing, connectivity, memory, security, and safety functions.
Semiconductor IP vendors that provide automotive-oriented architectures with functional safety, security, verification collateral, and long-term support can address the growing semiconductor requirements of next-generation vehicles.
Security-Enhanced Reusable IP
As semiconductor designs become more connected and applications become more security-sensitive, secure IP is gaining strategic importance. Semiconductor companies require architectures that can protect data, authentication mechanisms, communications, and sensitive system functions.
IP providers can differentiate through secure delivery mechanisms, strong access controls, encryption, traceability, verification, and security-oriented architecture.
Semiconductor IP Market Restraints and Challenges
High Licensing and Integration Costs
Advanced semiconductor IP can require substantial licensing commitments, integration resources, verification expenditure, and technical support. Smaller semiconductor companies and early-stage design firms may face budget limitations that restrict their ability to adopt premium third-party IP.
Flexible licensing structures, modular IP offerings, evaluation programs, development kits, and subsystem-level solutions can help reduce initial adoption barriers.
Semiconductor IP Security Concerns
Semiconductor IP can move between multiple organizations during design, verification, foundry preparation, integration, and production. This creates risks related to unauthorized access, design leakage, counterfeiting, and malicious modification.
Customers increasingly require strong assurance that licensed IP is protected and that vendors maintain secure processes. Security requirements can increase vendor qualification timelines and integration costs while making secure IP delivery and verification increasingly important.
Complex Integration and Verification
Integrating multiple third-party IP blocks into a complex SoC can create interoperability, timing, power, verification, and process-compatibility challenges. Semiconductor designers must ensure that individual IP blocks work reliably within the complete system architecture.
Consequently, vendors offering extensive verification collateral, documentation, process-qualified designs, technical support, and integration assistance can gain an advantage over suppliers offering standalone IP without sufficient development support.
Semiconductor IP Market Competitive Landscape
The competitive landscape includes major EDA and semiconductor IP companies as well as specialist providers focused on processor, GPU, interface, memory, connectivity, FPGA, security, and embedded architectures.
Competitive advantage increasingly depends on silicon-proven performance, process compatibility, verification quality, security, interoperability, technical support, licensing flexibility, and ecosystem relationships. Companies that can support customers throughout the complete design lifecycle are positioned to capture increasing value as SoC architectures become more complex.
Key Players
- Arm Limited – Processor IP, system IP, compute platforms, security technologies, and architecture support.
- Synopsys Inc. – Interface IP, memory IP, processor IP, security IP, verification technologies, and design enablement.
- Cadence Design Systems Inc. – Interface and memory IP, processor technologies, verification solutions, and semiconductor design platforms.
- Siemens EDA – Design IP, verification, simulation, implementation, and semiconductor development technologies.
- Imagination Technologies – GPU IP, AI accelerator IP, processor technologies, and graphics architectures.
- CEVA Inc. – DSP IP, wireless connectivity, AI processors, vision, audio, and sensing technologies.
- Rambus Inc. – Memory interface IP, DDR and HBM technologies, PCIe, CXL, controllers, and security IP.
- eMemory Technology Inc. – Embedded non-volatile memory IP and related semiconductor technologies.
- Achronix Semiconductor Corporation – eFPGA IP, FPGA technologies, accelerator solutions, and programmable architectures.
- VeriSilicon Holdings Co. Ltd. – GPU, NPU, video, display, connectivity, and customized semiconductor technologies.
Semiconductor IP Market Technological Innovations
AI Accelerator IP
AI workloads are creating demand for specialized processor and accelerator IP optimized for inference, parallel computing, and efficient data movement. Configurable AI engines can allow semiconductor companies to develop application-specific AI capabilities without designing every computational block internally.
Chiplet-Ready Interface IP
Chiplet architectures are increasing demand for high-bandwidth, low-latency interface technologies capable of connecting multiple dies within a heterogeneous system. Protocol compatibility, scalability, power efficiency, security, and validation are becoming key technology requirements.
Advanced Processor Architectures
Processor IP is evolving toward architectures optimized for application-specific workloads, including AI, automotive computing, edge intelligence, industrial automation, and high-performance infrastructure. Configurable architectures enable customers to balance performance, power consumption, and application requirements.
Advanced Memory IP
Increasing AI and data-processing workloads are creating greater demand for high-performance memory architectures. Memory IP providers are developing technologies designed to improve bandwidth, efficiency, integration, and reliability within increasingly complex SoCs.
Security-Enhanced IP
Embedded security is becoming an increasingly important component of semiconductor architecture. Secure IP can support authentication, encryption, trusted execution, access control, and protection of sensitive system functions.
Reusable Subsystem Platforms
IP vendors are increasingly moving beyond individual cores toward integrated subsystem offerings. Combining processor, connectivity, memory, security, and interface components into validated platforms can simplify customer integration and potentially increase the commercial value of each IP engagement.
Get Industry Snippets: https://www.businessmarketinsights.com/industry-overview/semiconductor-ip-market
Semiconductor IP Market Future Outlook
The Semiconductor IP Market is expected to maintain strong growth through 2033 as semiconductor architectures become more complex and system developers increasingly rely on reusable technology. The market is projected to increase from US$ 6.75 billion in 2025 to US$ 13.28 billion by 2033, representing an 8.83% CAGR during 2026–2033.
The next phase of market development will be strongly influenced by AI computing, custom silicon, chiplet architectures, advanced packaging, automotive electronics, edge computing, and high-speed connectivity. These applications require increasingly specialized processing, memory, interface, security, and acceleration functions, creating opportunities for IP suppliers with differentiated and validated architectures.
Frequently Asked Questions
What is the Semiconductor IP Market size in 2025?
The Semiconductor IP Market was valued at US$ 6.75 billion in 2025.
What will the Semiconductor IP Market size be by 2033?
The market is projected to reach US$ 13.28 billion by 2033, growing at a CAGR of 8.83% during 2026–2033.
Which segment leads the Semiconductor IP Market?
Design IP is the leading segment, accounting for 58%–61% market share in 2025 and projected to grow at 8.7%–9.2% CAGR through 2033.
Which Design IP category is growing rapidly?
Interface IP represents 23%–26% of Design IP and is projected to grow at 9.5%–10.0% CAGR, supported by chiplets, high-speed connectivity, heterogeneous computing, and increasing data movement requirements.
Which revenue source dominates the market?
License represented 55%–59% of market share in 2025 and is projected to grow at 8.2%–8.7% CAGR through 2033.
Which core type leads the Semiconductor IP Market?
Soft Core accounted for 62%–66% market share in 2025 and is projected to grow at 8.4%–8.9% CAGR through 2033, supported by its configurability and flexibility.
Which industry represents the leading application area?
Consumer Electronics accounted for 31%–34% market share in 2025 and is projected to grow at 8.5%–9.0% CAGR through 2033.
What is driving demand for semiconductor IP?
Major drivers include increasing SoC complexity, growing electronics adoption, shorter chip development cycles, AI acceleration, custom silicon development, automotive electronics, and high-speed connectivity requirements.
What are the major opportunities in the Semiconductor IP Market?
Major opportunities include AI-focused IP, chiplet-ready interfaces, custom silicon, automotive computing, security-enhanced IP, advanced memory architectures, and reusable subsystem platforms.
Why is Interface IP becoming strategically important?
Interface IP is becoming increasingly important because chiplet and heterogeneous architectures require reliable, high-speed communication among processors, memory, accelerators, and other semiconductor components.
Browse More Reports
- הפינה המשפטית
- ביטחון, אבטחה ומודיעין
- אבטחת אישים
- אבטחת מידע וסייבר
- רישוי עסקים
- אירועים תחת כיפת השמיים
- אבטחת מתקנים ואתרים
- מעברי גבול ו תעופה
- בתי ספר להכשרת ומכללות ביטחון
- כלי ירייה מטויחים וחנויות נשק
- אבטחה בתחבורה
- מנב"טים קב"טים קמעונאיים
- אחר
- הגנת הפרטיות
- מודיעין עסקי וארגוני
- פרשנות
- סיקורים
- רחפנים
- גילוי דעת
- כתבות
- מיומנו של קב"ט / מנב"ט

 Hebrew